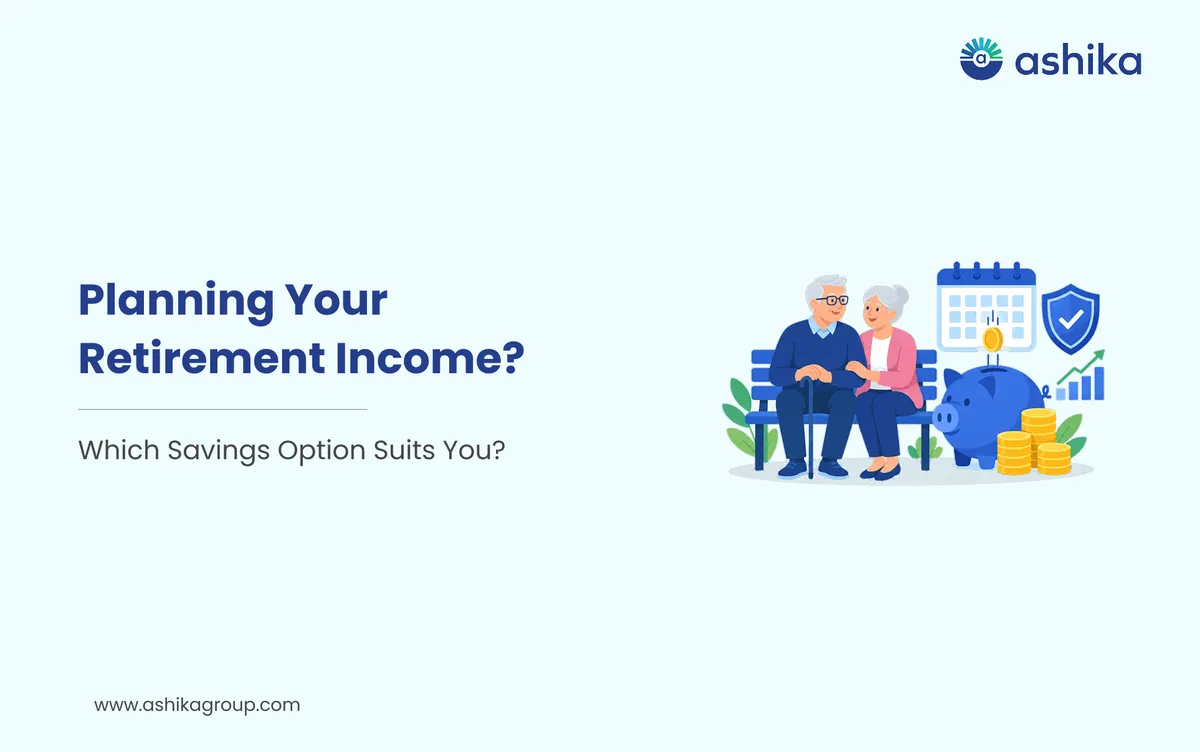
Retirement invariably brings a shift in the way people manage their money. With regular employment income either reduced or ceased altogether, many retirees are looking for ways to meet their monthly outgoings, manage their health care and preserve their savings. The right savings scheme can go some way to delivering a more predictable income stream, with the individual's own needs and level of risk tolerance in mind.
In India, the elderly can look at government sponsored savings schemes, bank deposits and a range of other financial products. Each of these will have its own eligibility criteria, its own interest rates, its own rules around withdrawals and its own tax treatment. It's absolutely vital to understand the differences between them as part of your retirement planning.
Table of Contents
- Savings Schemes for Senior Citizens in India
- 1. Senior Citizens’ Savings Scheme (SCSS)
- 2. Post Office Monthly Income Scheme (POMIS)
- 3. Bank Fixed Deposits (FDs)
- 4. National Savings Certificate (NSC)
- 5. Mutual Funds for Retirement Planning
- How to Choose a Suitable Savings Option
- How Financial Planning Services from Ashika Can Help
- Plan for Retirement with Greater Clarity
- Frequently Asked Questions
Savings Schemes for Senior Citizens in India
1. Senior Citizens’ Savings Scheme (SCSS)
The Senior Citizens' Savings Scheme is a government backed savings scheme for eligible older investors. It may be appropriate for people who have a lump sum available on retirement and are looking for a regular interest income.
For Oct-Dec 2026 the SCSS scheme rate is 8.2% p.a. Interest is paid quarterly and the normal account tenure is 5 years (with an extension facility available as per scheme rules). The maximum investment is ₹30 lakh per eligible individual.
For instance a ₹10 lakh deposit at 8.2% would yield around ₹20,500 in quarterly interest (before tax) assuming the rate is in force for the entire period.
SCSS has eligibility criteria and in the case of premature closure there could be deductions. It's vital to check the rules at the time of investment.
2. Post Office Monthly Income Scheme (POMIS)
Some people would rather have their income credited to them monthly rather than quarterly. The Post Office Monthly Income Scheme might be worth looking at in that scenario.
For Oct-Dec 2026 the scheme offers 7.4% p.a. with interest paid monthly. The maximum deposit is ₹9 lakh in the case of a single account and ₹15 lakh in the case of a joint account. The standard tenor is 5 years.
This can be useful for things like your groceries, your utility bills and other regular household expenses. The monthly interest will be taxable as normal and early closure is subject to scheme conditions.
3. Bank Fixed Deposits (FDs)
Fixed deposits are another familiar option for retirees. Investors deposit a lump sum down for a set tenure and you get interest according to the payment option you have chosen.ve interest according to the chosen payout arrangement.
Some banks offer higher interest rates to senior citizens than to other depositors. Rates, however, vary by bank, deposit amount and tenure. Compare the actual rates and premature withdrawal penalties before choosing an FD.
It may also be useful to divide savings over various maturities instead of locking the entire amount into a single long-term deposit. This can help provide access to funds at different points in time.
Bank deposits are not identical to government small-savings schemes. Check the applicable deposit insurance rules and limits, too.
4. National Savings Certificate (NSC)
The National Savings Certificate is a 5 year post office savings certificate which may be suitable for people who don't require any monthly income from the amount invested.ho do not need monthly income from the invested amount.
For Oct-Dec 2026 NSC offers 7.7% p.a. with interest accruing over the period rather than being paid monthly.
It could be considered for money set aside for a future expense. The interest though is not structured as a monthly payment and may not be suitable for a retiree who is reliant on a regular income to pay their bills.
Tax treatment and allowable deductions will of course be governed by the relevant tax rules and the investor's circumstances.
5. Mutual Funds for Retirement Planning
Some of the retirees will look at mutual funds as part of their overall financial plan. Debt funds will invest in bonds and other fixed income securities and hybrid funds will invest in a mix of different asset classes. All of these are subject to market risk and will not guarantee returns or capital protection.
Mutual funds should not be regarded as a straight replacement for guaranteed income savings. It's a case of the individual's circumstances determining whether they are appropriate. The individual's needs, their investment time frame, their liquidity requirements and their tolerance for value fluctuation all come into it.
How to Choose a Suitable Savings Option
Before investing, consider these questions:
- How much income do you require? Work out your monthly outgoings (healthcare, household etc) and include your insurance premiums.
- When would you actually need the money? Keep the cash accessible for emergencies rather than saving it all away.
- Can you stomach volatility? Market linked products may not be suitable for the funds you require for immediate outgoings.
- What are the tax implications? You need to look at the post-tax income rather than just the advertised interest rate.
- Are your savings properly diversified? Don't put all your eggs in one basket by relying entirely on one product or one maturity date.
Interest rates can vary between investment periods so it's always worth checking the most up to date official rates and scheme rules prior to investing.
How Financial Planning Services from Ashika Can Help
Choosing a savings scheme is just one element of retirement planning. The real issue is assuring that your savings, your regular income, your emergency fund and your future outgoings all work in harmony.
Financial planning services from Ashika can be looked at to see how various financial products might be suitable into an individual's wider financial picture. The financial planning conversation may assist with this depending on the range of services available and the investor's own needs.
- Income planning: working out how much money you might need each month in retirement.
- Product comparison: understanding the differences in tenure, payout frequency, liquidity and risk.
- Investment allocation (i.e. how your savings might be split across appropriate investment products).
- Future expenses: accounting for medical costs, family commitments and other anticipated obligations.
- Periodic reviews: looking at the plan again when expenses, income needs or your financial situation changes.
The point is to make financial decisions based on your actual requirements rather than just going for the product that's advertising the highest interest rate. You need to check what Ashika's actual service offering is and of course seek advice from appropriately qualified professionals for your individual circumstances.
Ready to open yours?
Free account opening · Paperless eKYC · Live in 10 minutes
Plan for Retirement with Greater Clarity
There is no one scheme that will be right for every oldie. SCSS will appeal to the eligible investor looking for income on a quarterly basis. POMIS gives you a monthly income. FDs give you the choice of various tenures and interest arrangements offered by the different banks. NSC may be the right vehicle for money you have earmarked for a future purpose. Mutual funds are a completely different risk/return proposition.
The right approach is to proceed by understanding your outgoings, your level of savings, your access to cash requirements and your level of risk tolerance. A considered financial plan will help you work through all of these before you go about deciding where your retirement savings should be.
Frequently Asked Questions
Which savings scheme is suitable for a senior citizen who needs regular income after retirement?
SCSS provides quarterly interest, while the Post Office Monthly Income Scheme (POMIS) pays interest every month. The choice depends on how frequently you need income.
What is the difference between SCSS and the Post Office Monthly Income Scheme?
SCSS offers quarterly interest at 8.2% p.a. for October–December 2026, while POMIS offers monthly interest at 7.4% p.a. Both have a five-year tenure, but their investment limits differ.
Can senior citizens withdraw their money before the maturity of these savings schemes?
Premature withdrawal is subject to scheme-specific conditions and may involve deductions. Check the applicable rules before investing, particularly if you may need access to the money early.
Are Mutual Funds a suitable alternative to fixed-income savings schemes for retirees?
They serve different purposes. Mutual Funds are market-linked and do not guarantee returns or capital protection, whereas schemes such as SCSS and POMIS offer interest at prescribed rates.
Should retirees invest all their savings in one scheme offering the highest interest rate?
Not necessarily. Retirement planning should account for monthly expenses, emergency funds, liquidity, taxes and risk. Spreading savings across suitable options and maturities can help manage these needs.
Was this article helpful?
Thanks for your feedback!
 7 min read